logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
Client Portal
logotype
logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
Client Portal
logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
Author: Eldon
family-news
News
19/11/2025by Eldon

New process for paying the High Income Child Benefit Charge

How is the High Income Child Benefit Charge (HICBC) calculated?

Child Benefit is provided to households with eligible children. However, if the claimant or their partner has an adjusted net income above £60,000, the higher earner is required to repay some or all of the benefit, known as the High Income Child Benefit Charge (HICBC).

The charge is applied at a rate of 1% of the Child Benefit for every £200 of adjusted net income over £60,000. This means the benefit is fully clawed back once the adjusted net income reaches £80,000.

How is HICBC collected?

HMRC has launched a new service that allows taxpayers to pay the High Income Child Benefit Charge (HICBC) through PAYE, removing the need for many to complete a Self-Assessment tax return.

Previously, anyone who owed HICBC had to register for Self-Assessment, even if the charge was under £2,000 and could technically be collected via their PAYE code. Now, if you’re only in Self-Assessment to pay HICBC, you can opt out and have the charge collected automatically through your salary.

In 2022/23, around 440,000 people were liable for HICBC. HMRC will soon be writing to around 100,000 individuals who appear to owe the charge but aren’t in Self-Assessment, encouraging them to use the new PAYE option.

While this change removes the admin burden for many, it’s still important to keep an eye on your adjusted net income each year to ensure you’re meeting your HICBC obligations.

How to switch to PAYE for HICBC:

  • First, de-register from Self-Assessment (HMRC won’t do this for you).
  • You can then start using the HICBC PAYE service the next day.

A welcome step towards simplifying the tax system for busy families.

Taxpayers who need to pay HICBC for both 2024/25 and 2025/26 may end up with two sets of HICBC charges in one year’s PAYE code. This would be either their 2025/26 or 2026/27 PAYE code, depending on when they file their 2024/25 tax return and when they chose to use the HICBC PAYE service.

Individuals who complete Self-Assessment tax returns for other reasons will still need to do so.

Opting out of Child Benefit

If you or your partner’s income is over £80,000, your Child Benefit will be fully withdrawn through the High Income Child Benefit Charge (HICBC). In this case, you may choose to opt out of receiving Child Benefit payments to avoid the need to repay them.

There are several ways to do this:

  • Via your online Personal Tax Account
  • By completing an online form
  • By phoning or writing to the Child Benefit Office

Please note: Agents cannot opt out on behalf of clients, the claimant must do this themselves.


Even if you don’t want to receive the payments, it’s still a good idea to register for Child Benefit. Why?

  • The non-working or lower-earning parent may receive Class 3 National Insurance credits, which count towards their State Pension.
  • Registration also ensures your child is automatically sent a National Insurance number before they turn 16.

This can be a wise move for long-term financial planning, even if no payments are made.
Read More
Adam
News
04/11/2025by Eldon

Recent Success at Eldon

Autumn has already seen some great achievements at Eldon, which we’re pleased to share.

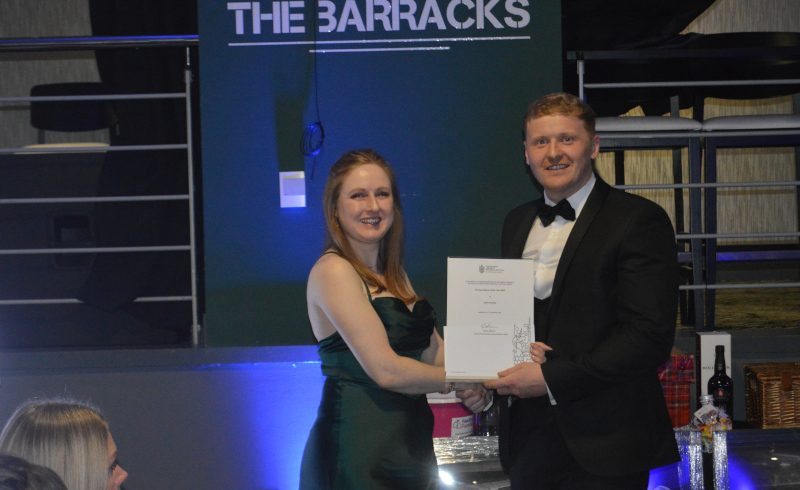
To kick off the season, Director of Operations and Chartered Financial Planner, Adam, won the 2025 ‘Deputy President’s Young Achiever of the Year Award’!

The accolade is awarded by the Chartered Insurance Institute, a key professional body in the insurance and financial planning profession. It was created to recognise and applaud outstanding achievements of those under age 35 within the industry, with a particular focus on professional excellence, delivering value to the profession, and championing career progression.

In October, Chartered Financial Planner, Beth, successfully completed the final exam needed to become a Fellow of the Personal Finance Society.

The Personal Finance Society is part of the Chartered Insurance Institute. Fellowship demonstrates that the holder has attained and maintained the most prestigious level of professional qualification that they award (the Advanced Diploma in Financial Planning). It is also a key indicator of ongoing commitment to professional standards and personal development, and it is a great achievement within the profession.

Well done to both, and may the success continue!

Read More
IMG_2968
News
29/09/2025by Eldon

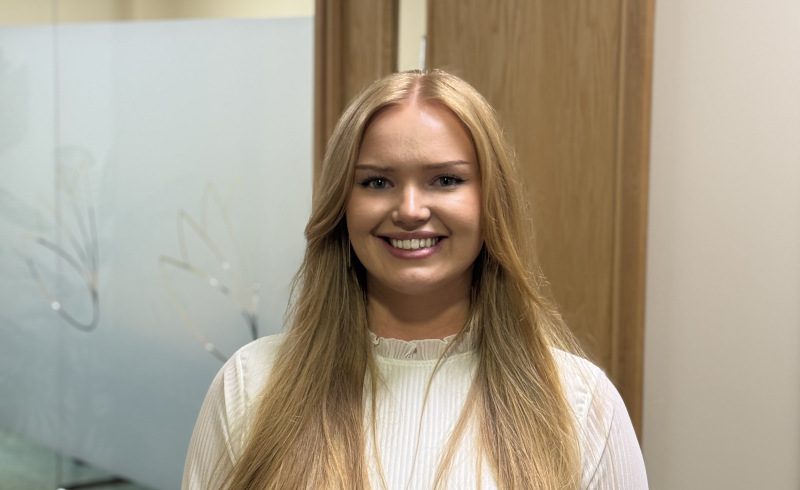
Welcome, Amy!

Earlier this month, Eldon welcomed Amy Laroche as a new addition to our paraplanning team. We are excited to have Amy as part of our team, and we can’t wait to see what she achieves.

Here is a short introduction from Amy:

“My journey into financial services began in 2023 while working as an Independent People’s Advocate. I saw firsthand how money mismanagement and poor financial planning can impact a person’s life, and it sparked within me an interest in helping people navigate their finances. I took the leap into the industry the following year.

I joined Eldon as a Trainee Paraplanner, drawn to their holistic approach and strong client-first values. I am currently working towards my Diploma in Regulated Financial Planning, with the goal of becoming Chartered while at Eldon.

Outside of work, I am passionate about travelling and art. Some highlights so far include seeing “Starry Night” in New York, “The Kiss” in Vienna, and “The Scream” in Oslo. I’m on a mission to visit all seven continents, enjoying every new culture and art gallery along the way.”

Read More
retirement
News
17/09/2025by Eldon

From Saving to Spending: The Psychological Shift in Retirement

For decades, most of us follow a well-worn path: earn, save, invest, repeat. We work hard to build a retirement fund that will one day give us the freedom to live on our terms, but when retirement finally arrives, spending that money can feel strangely difficult.

We’ve worked with many people who are financially prepared for retirement but find themselves emotionally unprepared for the shift from saving to spending. This is more common than you might think, and it all comes down to psychology.

A Lifetime of Habit

Throughout your working life, the focus is often on security and growth, which saving is a major part of. It also provides a sense of control, progress, and a buffer against life’s uncertainties. This habit, often reinforced over a 30 to 40-year period, isn’t just a financial strategy; it can become part of your identity. So, when retirement comes, changing your mindset can take some time.

The Fear of Running Out

Running out of money in retirement is also an entirely rational fear, given that this phase of life typically lasts 30 years or more. However, this can sometimes lead to overly cautious behaviour. In some cases, it may mean you spend far less than is affordable, missing out on opportunities to enjoy life while you are often most able.

This is where thoughtful financial planning becomes about more than just numbers – it’s about reassurance and confidence. By stress-testing financial plans, running through different scenarios, and updating models as life moves on, we can assess whether your retirement lifestyle and income are sustainable, even with extra holidays, home upgrades, or helping the next generation financially.

Balancing Prudence and Peace of Mind

Our job as Financial Planners is to help clients live with financial confidence, which includes guiding you through the emotional aspects of retirement. We provide the tools and plans to help you:

  • Understand how much you can spend safely
  • Set realistic and fulfilling lifestyle goals
  • Adjust spending patterns as life evolves
  • Reduce anxiety around investment market movements

Ultimately, the goal is not just to avoid running out of money – it’s to avoid running out of life before you’ve had chance to thoroughly enjoy the wealth you’ve created.

If you would like to discuss anything raised in this article with one of the team, please do reach out.

Read More
blank-792125_1280
News
27/08/2025by Eldon

Lasting Power of Attorney Application Fees to Increase

The Ministry of Justice has confirmed that application fees for Lasting Powers of Attorney (LPA) will rise from £82 to £92 per document from 17th November 2025, subject to parliamentary approval. Repeat applications will also increase from £41 to £46.

This change reflects the government’s aim to align fees more closely with the cost of delivering services via the Office of the Public Guardian (OPG).

Now is an ideal time to consider putting LPAs in place.

A Lasting Power of Attorney (LPA) is one of the most important legal documents you can have in place as part of your financial planning. It gives someone you trust the legal authority to act on your behalf if you become unable to make decisions due to illness, injury, or declining mental capacity or if you don’t want to.

There are two types of LPA:

  • Property and Financial Affairs LPA – lets your attorney manage your finances, pay bills, sell property, and handle investments.
  • Health and Welfare LPA – allows your attorney to make decisions about your medical treatment, care arrangements, and daily routine if you’re unable to do so yourself.

Without an LPA in place, your loved ones would need to apply to the Court of Protection to make decisions on your behalf – a lengthy, costly, and often stressful process. Crucially, they may not be given the authority to act in the way you would have wished.

With application fees set to rise and the OPG now operating more efficiently (having cleared registration backlogs and improved service levels), it’s a good time to act.

At Eldon, we strongly recommend reviewing your estate planning and ensuring LPAs are in place as part of your financial strategy.

If you would like to speak with your Financial Planner here at Eldon, then please do not hesitate to get in touch with us.

Read More
elderly-2914879_1280
News
05/08/2025by Eldon

State Pension Age Review

The Pensions Act 2014 requires the government to conduct a periodic review of the State Pension age (SPA). The first review concluded in 2017, and the second review concluded in 2023. The government has announced the launch of the third review of State Pension age in July 2025, which is set to conclude in 2029. This review will consider whether the rules around pensionable age are appropriate, based on the latest life expectancy data and other evidence.  

As a reminder, the current timetable for the SPA, is shown below:

  • SPA will increase from 66 to 67 – between April 2026 and April 2028
  • SPA will increase from 67 to 68 – between April 2044 and April 2046

The announcement comes following warnings from experts that people looking to retire in 2050 are on course to receive £800 per year less than current pensioners. This is due to the fact that 45% of working-age adults are not contributing into their pensions, with concerns that the cost of living crisis is preventing people from investing in their retirement.

The government have confirmed that there will be no further increases to National Insurance contributions under this parliament, both employee and employer, to help fund the issue. They have also confirmed that the pensions triple lock, the guarantee that the state pension rises in line with average earnings, inflation or 2.5% – whichever is highest – would not be reconsidered as part of this review.

Any recommendations from the review will take time to implement and the government remains committed to the principle of providing 10 years’ notice of changes to the SPA.

Read More
NF Careers
News
28/07/2025by Eldon

Supporting Future Careers

Beth and Natasha recently had the pleasure of attending the Careers Fair at Park View Academy in Chester-le-Street. The event was a great opportunity to engage with students, share insights into the financial planning profession, and highlight the rewarding career paths available within the sector.

Throughout the event, students were able to ask questions, explore different industries, and gain practical advice directly from professionals, helping them make more informed decisions about their future careers.

Eldon is proud to support events that promote career awareness. We aim to encourage young people to consider a future in financial planning whilst continuing to support financial education within local communities.

Read More
Walk
News
14/07/2025by Eldon

Fighting Alzheimer’s Disease – One Step At A Time

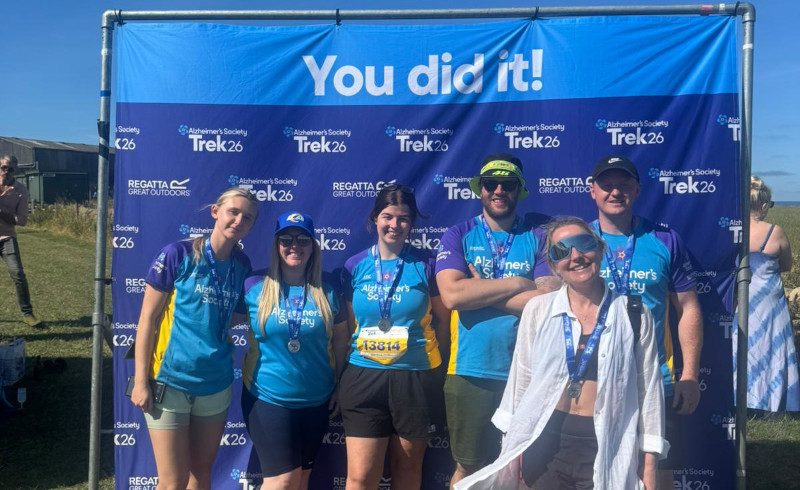
We’re incredibly proud of our team for undertaking the 2025 Alzheimer’s Society Trek through the North York Moors on Saturday.

The experience was a far cry away from our 2023 Ullswater Way trek, which we undertook in wild and stormy weather in the Lake District. This North York Moors challenge was blisteringly hot, with no breeze and a strong sun!

With plenty of water, good spirits, and team camaraderie, our two teams completed their challenge, raising almost £4,000 for Alzheimer’s Society as a result of their dedication.

We’re so proud of them!

Donations to our fundraising page will stay open for another week or so. Eldon is matching all fundraising so whatever you give will be doubled to the charity: https://www.justgiving.com/page/eldon-financial-alzheimer-trek-2025

Every donation, no matter the size, will help bring us closer to a world where dementia no longer devastates lives.

Together we can take a step towards a better future.

Well done, Team!

Read More
SamWebsite
News
10/06/2025by Eldon

Eldon Success!

We are delighted to announce that Trainee Paraplanner Samantha has now gained her Diploma in Financial Planning.

Samantha started her studies in March 2024 whilst she was working full time in clinical trials at the NHS before joining Eldon in April 2025 to support us with both administration and paraplanning.

Samantha will now be working towards the Advanced Diploma in Financial Planning with a view to achieving Chartered Status.

Well done, Samantha! We are looking forward to seeing what you achieve next!

Read More
homeinsurance
News
27/05/2025by Eldon

Inheritance Tax on the Rise

Inheritance tax (IHT) continues to generate increasing revenue for HMRC, with April 2025 alone bringing in £800 million. This is a rise of £97 million compared to April 2024, or a 13.8% year-on-year increase. The broader picture shows the 2024/25 tax year setting a record £8.2 billion in IHT receipts.

This growth isn’t new; since 2009/10, when inheritance tax brought in £2.4 billion, receipts have steadily climbed—both in real terms and as a proportion of the UK’s GDP. In fact, IHT now makes up an estimated 0.28% of GDP, nearly double the 0.15% seen in 2009/10.

Why Are Receipts Increasing?

A few key drivers are contributing to this trend. Since March 2021, the nil-rate bands for inheritance tax have been frozen—a policy set to continue until 2030. Meanwhile, rising property prices, often the biggest asset an individual has, and strong investment markets have increased the value of many estates, pushing more of them above the tax threshold.

And the upward pressure isn’t over. The Autumn Budget 2024 announced significant reforms to Agricultural and Business Relief (effective April 2026) and the inclusion of unused pensions in estates from April 2027. These changes are likely to see the inheritance tax revenue increase further for HMRC in the future.

What Does the Future Hold?

According to the Office for Budget Responsibility, nearly 10% of estates will be subject to inheritance tax by 2030. That’s more than double the 4% of estates affected in 2020/21.

This shift is prompting more individuals and families to consider how inheritance tax might affect their legacy and whether steps can be taken to reduce the impact.

“A Voluntary Levy”?

To quote former Labour Chancellor Roy Jenkins:

“Inheritance tax is, broadly speaking, a voluntary levy paid by those who distrust their heirs more than they dislike the Inland Revenue.”

While tongue-in-cheek, the quote underscores the importance of effective inheritance tax planning.

That said, everyone’s priorities are different. Some value the reassurance of retaining capital for life’s uncertainties and are accepting of any potential inheritance tax that comes with this, whilst others prefer to pass on as much as possible to loved ones or spend their wealth during their lifetime.

Planning Ahead

There’s no one-size-fits-all approach to inheritance tax planning. Each situation is unique, and careful, tailored planning is essential to align financial strategy with personal goals and values.

What’s more, IHT planning isn’t static. Legislative changes can undo previous strategies, and personal circumstances often evolve. Regular reviews and proactive planning are crucial to staying on course.

If you would like to speak with your Financial Planner here at Eldon, then please do not hesitate to get in touch with us.

Read More
  • 1
  • 2
  • 3
  • 4
  • 5
Contact Us

Eldon Financial Planning Limited

1 Parsons Court

Welbury Way

Newton Aycliffe

County Durham

DL5 6ZE


Telephone: (01325) 318000

Office Hours

Monday to Thursday:

9:00am – 4:30pm

Friday:

9:00am – 12:30pm

Important

The guidance and/or advice contained in this website is subject to the UK regulatory regime and is therefore restricted to consumers based in the UK.

The Financial Ombudsman Service is available to sort out individual complaints that clients and financial services businesses aren’t able to resolve themselves.

To contact the Financial Ombudsman Service please visit:

www.financial-ombudsman.org.uk

Useful Links
Important Information
Privacy Information
Recruitment

Eldon Financial Planning Limited is authorised and regulated by the Financial Conduct Authority No. 221354

Registered in England & Wales No. 4561871