logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
Client Portal
logotype
logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
Client Portal
logotype
  • Home
  • Why Eldon
    • About Us
    • Meet The Team
    • Our Fees
    • Qualifications
    • Testimonials
  • Our Services
    • What We Do
    • The Eldon Process
    • Lifetime Financial Planning
    • Retirement Planning
    • Investment Planning
    • Tax Planning
  • People Like You
  • Charity
  • News
  • Contact Us
News

Category: News

Designer (2)_edited
News
29/10/2026by Eldon

Autumn Budget 2026: Key Takeaways

The Budget announced on 28th October 2026 includes changes that could affect your savings, first-home deposit, retirement income or business.

Below is a summary of the key announcements most relevant to your Financial Planning. 

Higher tax on savings and rental income from 6th April 2027

From 6th April 2027, taxable savings income will be taxed at 24% for basic-rate taxpayers, 44% for higher-rate taxpayers and 49% for additional-rate taxpayers across the UK. The same rates will apply to property income in England, Wales and Northern Ireland.

These increases are in addition to the two percentage point increases announced in the 2025 Budget for the same date. The government says 84% of income taxpayers will not be affected. Dividend tax rates are unchanged.

ISAs and first-time buyers

  • Cash ISAs: the limit remains £20,000 from 6th April 2027. The planned reduction to £12,000 for under-65s will not go ahead.
  • First Time Buyer ISA: this replaces the Lifetime ISA for new savers from 6th April 2029. Savers can contribute up to £4,000 a year. A 25% government bonus, capped at £20,000, is paid when funds are withdrawn for a qualifying first home worth up to £450,000. There is no upper age restriction. Existing Lifetime ISA holders can continue under the current rules.
  • Lifetime ISA withdrawals: from 29th October 2026, first-time buyers purchasing a home above the £450,000 limit can withdraw their funds with a 20% charge, reduced from 25%.
  • First-time investors: the government will work with the industry on a new incentive for first-time stocks and shares ISA investors. Details are not yet confirmed. 

Pensions and retirement 

  • State Pension increases: until 5th April 2029, the State Pension will rise each year by the highest of 2.5%, inflation or earnings growth (the triple lock). From 6th April 2030, the adjusted Triple Lock will apply, so the State Pension rises each year by the highest of 2.5%, inflation, or the amount required to maintain its value relative to earnings as reached in April 2029.
  • Pension Tax Allowance: from 6th April 2027 to 5th April 2030, pensioners whose total income is no more than the full new State Pension will pay no income tax. This applies automatically. It does not increase the Personal Allowance for all pensioners.
  • Inherited pensions: the two-year rule is removed for payments made on or after 28th October 2026. Beneficiaries will no longer be taxed solely because tax-free pension or lump sum death benefits are paid more than two years after the member’s death.

No change was announced to pension tax relief or the tax-free lump sum in the Budget document. Unused pension funds are still expected to fall within inheritance tax from 6th April 2027, based on the earlier announcement.

Capital gains and business owners 

  • Business Asset Disposal Relief: from 6th April 2027, the lifetime limit for gains taxed at the reduced 18% rate falls from £1m to £500,000.
  • Founders’ Relief: from 6th April 2027, qualifying founders of high-growth, innovative companies can pay 10% capital gains tax on up to £10m of lifetime gains. The detailed design is subject to technical consultation.
  • Share schemes: from 6th April 2027, Company Share Option Plan will be known as EMI2. The individual option limit rises to £120,000 and the exercise period extends to 15 years. Technical changes will also make Venture Capital Trusts, EIS and SEIS easier to use.
  • Stamp duty on shares: a new Securities Transfer Tax will replace Stamp Duty and SDRT from late 2027. 
  • Trading allowance: the income tax trading allowance increases from £1,000 to £3,000 from 6th April 2027. 

Household bills and cost of living 

  • £100 Household Energy Payment: up to 20 million households in council tax bands A to D in England will receive this through the council tax system from January 2027. The total cost is £2.6bn.
  • VAT on household electricity: the rate falls from 5% to 0% from 1st October 2026 to 1st July 2027. This is expected to reduce the April 2027 price cap by around £50. Ofgem has also been asked to remove gas standing charges, currently around £108 a year, by the end of 2027 or as soon as possible afterwards. 
  • Fuel duty: the 5p cut continues, and the planned inflation increase is delayed until 1st July 2027. 
  • Bus fares: fares in England outside London will be capped at £2 for a year from 1st January 2027. 
  • Food prices: from 26th November 2026, import tariffs are suspended on 101 food products until 31st December 2028. This sits alongside an earlier package suspending tariffs on 135 food products from 21st June 2026.
  • National Living Wage: the rate rises by 3.9% to £13.21 an hour from 1st April 2027. 
  • Mileage rates: the tax-free rate for the first 10,000 business miles rises to 55p from 6th April 2026. The rate for miles above this rises to 35p from 6th April 2027. 
  • Student loans: interest on Plan 2 and Plan 3 loans is capped at 6% from 1st September 2026 to 31st August 2027.

What stays the same 

The main rates of Income Tax, National Insurance and VAT are unchanged.

Income Tax thresholds and Inheritance Tax allowances are set to remain frozen until 5th April 2031. As incomes rise, more taxpayers will move into higher tax bands.

From April 2029, self-assessment taxpayers who make payments on account will make smaller, more regular payments during the year. From July 2029, HMRC will also be able to recover lower-value tax debts directly from the bank accounts of people who can afford to pay but repeatedly fail to do so.

In Summary

The Budget brings changes to savings and rental income tax, pensions and business reliefs, alongside support with household costs. However, cash ISA limits remain unchanged, with no changes announced to pension tax relief or tax-free lump sums. Some measures still await legislation or further detail.

It remains important to take a calm, considered approach to your Financial Planning when considering changes announced in a Budget. For our clients, we will review the implications for your Financial Plan and recommend adjustments where appropriate, keeping your long-term objectives at the heart of any decisions.

If you have any questions or would like to discuss how the Budget could affect your plans, please get in touch. We’re happy to help.
Read More
ukgov
News
26/10/2026by Eldon

Budget Speculation: keeping the focus on what matters

Budget season brings with it a familiar mixture of headlines, predictions, and rumours. Over the coming days, you’ll likely see plenty of commentary about what could change on 28th October.

But amongst all that noise, we think there is one simple message worth keeping in mind: keep the focus on what is important behind your Financial Plan.

Your Financial Plan isn’t really about tax rates, allowances, or investment rules. Those things are important, of course, but they are the tools we use to help you achieve what really matters to you.

That might be enjoying retirement with confidence, spending more time with family, travelling, helping children or grandchildren with their own plans, or simply having the reassurance that you have enough to enjoy life.

The Budget may change some of the rules around your Financial Plan, but it doesn’t change what the money is for.

Last year provides a useful reminder of why keeping that perspective matters. There was considerable speculation about possible changes to pension tax-free cash and some people in the UK acted before the Budget, only for the anticipated changes not to happen.

That’s why important financial decisions are generally better made calmly, with the facts in front of us, rather than in response to speculation or a headline that may not come true.

Once the Budget has been delivered and the detail is clear, we can consider what any changes mean for your Financial Plan. If changes are needed, we will build them into your Financial Plan as part of our regular planning service. But the things your plan is designed to help you achieve are unlikely to have changed at all.

In the meantime, if something you read or hear is worrying you, please get in touch. We’re always happy to talk it through.

Read More
welcomekatie
News
12/10/2026by Eldon

Welcome, Katie!

In September, Eldon welcomed Katie Watts as a new addition to our paraplanning team. We are excited to have Katie join our team and can’t wait to see what she achieves.

Here is a short introduction from Katie:

“After graduating from Newcastle University in 2011 with an honours degree in Law, I spent several years working in the Revenues and Benefits Department of a Local Authority where I developed an understanding of the state benefits system and provided advice and guidance to benefit claimants. I then moved into financial services in 2018 and have since worked for two different IFA firms before joining Eldon in 2026. This has given me the opportunity to work with a wide variety of clients, each with their own circumstances, goals and planning needs. I enjoy the detail of problem-solving involved in paraplanning, but also the human side of financial planning – understanding what matters most to clients and putting the right solutions in place for them.

I completed my Diploma in 2022 and I am now working towards the Advanced Diploma and Chartered Status.

Outside of work I’m Mum to my beautiful daughter, and when I do get some spare time, it’s usually spent with family and friends. I also enjoy cooking, eating out, reading, and have recently rediscovered an enthusiasm for crochet.

Professional Achievements:

  • Diploma in Regulated Financial Planning
  • Certificate in Discretionary Investment Management”

Read More
piggy-bank-2889042_1280
News
30/09/2026by Eldon

Is Your Savings Account about to Mature?

More than £119 billion held in fixed-rate savings accounts are due to mature before the end of 2026. If some of that money is yours, now is a good time to think about what you want to do with it next. 

When your fixed-rate account matures, the interest rate you have been receiving will usually come to an end. Depending on the terms of your account, your provider may automatically move your money into another savings account, which could pay a lower variable rate. 

Research commissioned by Skipton Building Society suggests that, in some cases, this could result in returns falling by almost half. This will not apply to every saver, but it highlights why it is worth checking what will happen to your money before your fixed term comes to an end. 

This is especially important given that returns on the top fixed-rate savings accounts are at their highest level in years, with some paying up to 5.12% at the time of writing. Therefore, taking the time to review your options could help you make sure your savings continue to work as hard as possible for you. 

Why it pays to act early 

If you find it easy to put off making a decision about your savings, you are not alone. In Skipton Building Society’s research, 39% of people said they rarely or never move their savings, while 31% said they had experienced what was described as “money-moving paralysis”. 

However, reviewing your options doesn’t have to be complicated or time-consuming, and the process of switching savings accounts is more straightforward than you may think. The important thing is to understand what is going to happen and make an active decision, rather than allowing your money to move automatically without checking the new terms. 

Your maturity checklist 

As your maturity date approaches, it is worth checking: 

  • When your fixed-rate deal ends. 
  • What interest rate will apply once the fixed term has ended. 
  • Whether your provider will automatically move your money into another account. 
  • What other rates are available elsewhere 
  • Whether there is a deadline for choosing a new account or withdrawing your money. 
  • Whether your current arrangements still provide the level of return, access and flexibility you need. 

A short review before your account matures could help you avoid leaving your money somewhere that no longer suits your circumstances. 

Look beyond the interest rate 

The end of a fixed-rate deal can also be a useful opportunity to think about what you are actually saving the money for. The interest rate is important, but it is not the only consideration. You should also think about: 

  • When you are likely to need access to the money. 
  • How important easy access is to you. 
  • Whether you have other savings available for unexpected expenses. 
  • How your savings fit alongside your wider financial objectives. 

For some people, keeping their money in cash will remain the most appropriate option. For others, particularly those with longer-term goals, it may be worth considering whether other options could form part of their financial plan. 

There is no one-size-fits-all answer, and the right approach depends on your circumstances, your goals, and when you expect to need the money. 

If you are unsure what to do when your fixed-rate savings account matures, speaking to one of our team can help you understand the options available and how they could fit into your wider financial plans. We would be happy to help you consider your next steps.

Read More
wallet-g991636795_1280
News
02/09/2026by Eldon

HMRC Contacting Low Earners About Missed Pension Tax Relief

HM Revenue & Customs (HMRC) has begun contacting around one million people who may have missed out on pension tax relief because their workplace pension scheme operates under a Net Pay Arrangement. Under Net Pay, pension contributions are deducted from earnings before income tax is calculated. This normally provides automatic tax relief at the individual’s marginal tax rate. However, for individuals earning below the Personal Allowance (currently £12,570), there is no income tax liability for the pension contribution to reduce. Consequently, these workers do not receive tax relief on their contributions.

By contrast, under a Relief at Source arrangement, contributions are taken after tax, and the pension provider claims a 20% basic-rate top-up directly from HMRC and adds it to the pension contribution. This means that even someone who does not pay income tax can receive the 20% basic-rate top-up.

The introduction of the Low Earner’s Pension Payment is intended to address this difference and ensure that lower-paid pension savers receive a more consistent level of tax relief, regardless of whether their workplace pension uses a Net Pay Arrangement or Relief at Source.

Who is affected?

HMRC estimates that around 1.2 million people are eligible for top-ups, with roughly three-quarters expected to be women.

You may be eligible if you:

  • Contributed to a workplace pension using a Net Pay Arrangement; and
  • Had total taxable income below (or close to) the Personal Allowance in the relevant tax year.

Eligibility applies from the 2024/25 tax year onwards and is assessed separately for each tax year, meaning some individuals may be entitled to payments covering multiple years.

How much could you receive?

HMRC estimates that eligible individuals will receive around £70 per year on average, although the actual amount will depend on their pension contributions and individual circumstances.

The top-up is paid directly to the individual and is intended to address the difference in tax relief received under the two arrangements. It does not change how workplace pension contributions are made.

What do you need to do?

HMRC will identify potentially eligible individuals and contact them directly, rather than individuals needing to make a claim.

HMRC’s latest guidance confirms that eligible individuals should wait to be contacted, either by post or through their Personal Tax Account. Once contacted, they should follow the instructions provided to receive the payment. There is no need to contact HMRC in advance or ask their employer or pension provider to make a claim on their behalf.

Payments relating to contributions made during the 2024/25 tax year will begin in the coming months, with HMRC taking a phased approach to the rollout through the remainder of 2026 and into early 2027.

HMRC has also confirmed that it will never ask individuals to transfer money in order to receive the payment, nor will it ask for PINs or passwords.

If you receive any correspondence from HMRC regarding this and would like help understanding what you need to do, please do not hesitate to get in touch with a member of the team.

Read More
pexels-puddle-1853607
News
18/03/2026by Eldon

Weathering Volatility: Taking The Long View

Global markets experienced some fluctuations the past few weeks following the US attacks on Iran, with oil prices seeing the most noticeable increase, and it is likely that markets will remain volatile as the situation evolves.

Rising geopolitical tensions often lead to short-term movements in global financial markets, as investors weigh the potential implications for energy supply, oil prices, and inflation. While sudden fluctuations can feel unsettling, they are typically temporary responses to unfolding events rather than lasting changes to the long-term outlook for investments.

It’s important to remember that short-term movements are a normal part of the investment process; well-diversified portfolios built with resilience in mind are designed to weather such storms by spreading investments across a range of regions, sectors, and asset types.

History shows that markets have repeatedly navigated uncertainty, recovered from disruptions, and continued to progress as conditions stabilise. Therefore, reacting quickly to short-term market movements often does more harm than good. We encourage you to keep calm amid the uncertainty. Maintaining a long-term perspective has often proven to be the more effective approach for investors seeking sustainable growth over time.

As always, we are monitoring developments closely and if we believe any action is needed before your next scheduled review, we will contact you.

In the meantime, if you have questions or would like to talk things through, please reach out. We are here to provide guidance, reassurance, and support every step of the way.

Read More
Media (13)
News
02/03/2026by Eldon

Celebrating the Next Generation

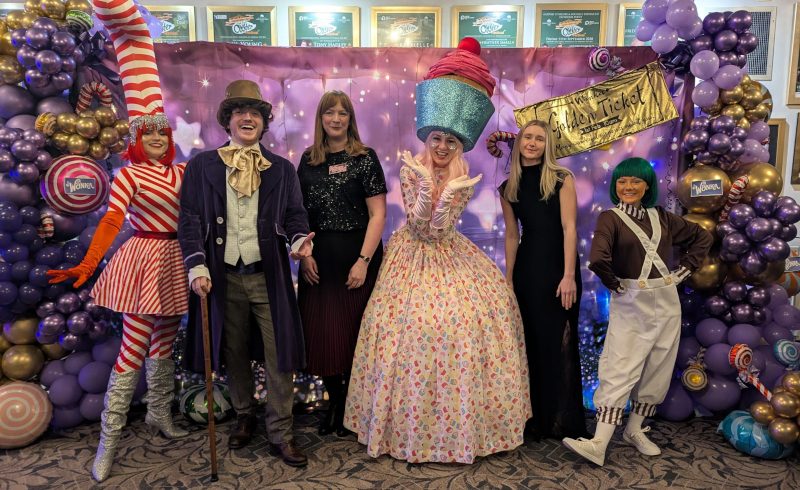
Members of the Eldon team were delighted to attend the High Sheriff Youth Awards last month, celebrating young people across County Durham.

Organised by Point North (the community foundation for County Durham and Tees Valley), and supported by the High Sheriff of Durham, the Awards are presented each year to recognise the extraordinary contribution of local community groups. Winning groups are awarded funds to continue supporting young people across County Durham, Darlington, Hartlepool, and Stockton.

This year, Hardwick Hall Hotel in Sedgefield was transformed into a scene straight from Willy Wonka’s Chocolate Factory, truly bringing the magic of the evening to life. A total of £35,000 was awarded across twelve groups, helping them to continue with, and strengthen, their work. Many groups also spoke of using some of the funds to provide enriching residential trips and experiences, things which would simply be too costly for them to offer otherwise.

This year’s High Sheriff of Durham, Michael Poole, highlighted the importance of the groups’ work and continuing to support them:

“The judging panel were certainly tested by the extremely high calibre of the applications received. The awards aren’t about being perfect. They’re about stepping up, showing kindness, helping, and making a difference. That’s exactly what young people across this county are doing – supported every step of the way by incredible organisations that give them the space and guidance to thrive. What you’re all doing is what makes County Durham a stronger, kinder and more connected place.”

As an ongoing supporter of Point North, we were honoured to attend this year’s Awards and the team left with a real sense of pride in our communities (as well as far too much chocolate).

Read More
taxoffice
News
16/02/2026by Eldon

Important Update: HMRC Changes How You Receive Tax Refunds

HM Revenue & Customs (HMRC) has updated its process for issuing tax refunds to employees and pensioners under PAYE. If you are due a refund, you may no longer receive it automatically and may need to claim it.

Previously, when HMRC issued a P800 tax calculation showing a refund was due, they would automatically send a cheque in the post if you did not claim the refund online within 21 days.

This process has now changed. HMRC has stopped issuing automatic cheques for most P800 refunds. If you receive a calculation showing you are owed money, you must now take action to claim it. If no claim is made, the money will remain with HMRC.

The Quickest Way to Claim

HMRC advises that the fastest way to check if a refund is due and to claim it is via the HMRC App:

  1. Open the HMRC App and tap the ‘Pay As You Earn (PAYE)’ section.
  2. If a refund is due, you’ll see a tax calculation and a green ‘Claim’ button.
  3. Tap the button to submit your claim.
    • Bank Transfer: Funds are typically paid directly into your bank account within 5-10 working days.
    • Cheque: If you prefer a cheque, it can take up to 6 weeks to arrive.

If You Don’t Use Online Services

If you do not have access to the HMRC app or online account, you can still claim your refund using the instructions on your P800 letter.

You can claim via the government website here (you will need your P800 reference number and National Insurance number), or by calling HMRC directly.

Check Your Calculation Carefully

Before claiming any refund, it’s important to review your tax calculation to ensure the figures are correct. Common areas where errors occur include:

  • Savings Interest: HMRC receives data directly from banks, but this can sometimes be incorrect or duplicated. Check that the interest figure matches your records and excludes any interest earned in ISAs (which is tax-free). If you hold joint accounts, check that only your share (usually 50%) is included.
  • Pension Contributions: If you are a higher or additional rate taxpayer, check that your personal pension contributions are accurately reflected. Relief is not always applied automatically to contributions made outside of salary sacrifice schemes.
  • Gift Aid: Ensure any charitable donations made under Gift Aid are included, as you may be entitled to additional tax relief.  

If you receive a tax calculation from HMRC and would like us to review it, please don’t hesitate to get in touch with one of the team.

Read More
sailing-7443742_1280
News
02/02/2026by Eldon

Why the Best Investment Decisions are Made in Calm Conditions

Experienced sailors don’t wait for rough seas to think about how they’ll respond. They prepare in calm conditions, knowing storms are inevitable. Investors face the same reality. Market volatility is not a possibility, it’s a certainty, and preparation determines whether you stay the course or abandon ship at the worst moment.

Investors will almost certainly face periods of market stress. Over history, global equities have experienced regular downturns, including sharp falls driven by recessions, financial crises, political uncertainty, and global shocks.

What’s easy to forget in the middle of a downturn is that a bad spell doesn’t necessarily lead to a bad year, or a bad long-term outcome. Even after significant mid-year declines, markets have often recovered to finish the year higher or gone on to deliver strong returns in subsequent years. This reinforces a crucial lesson: reacting emotionally to market falls can be more damaging than the falls themselves.

We can’t control the weather at sea, just as we can’t control market movements. What we can control is how we respond to them. Avoiding panic, sticking to a well-considered plan, and remaining invested through market storms are often the most reliable ways to protect long-term outcomes.

Read More
piggy-6040691_1280
News
19/01/2026by Eldon

Discretionary Trust Tax Changes

Managing a discretionary trust comes with complex tax rules, and the recent Budget announcements mean some important changes are on the horizon.

We have provided a summary of the key changes below:

Discretionary Trust Income

The budget announced a 2% rate increase on dividends from 6th April 2026 which apply to the ordinary and higher rates only. No changes were made to the dividend trust rate of 39.35%.

From 6th April 2027, the tax rates on savings and property income received by discretionary trusts will increase by 2%. This means that the current trust rate of 45% for non-dividend income from discretionary trusts will increase to 47% where it relates to savings or property.

Chargeable Gains from Investment Bonds

Investment bonds are a popular option for discretionary trusts, partly due to the high rates of tax on other types of income, but also the administrative simplicity they provide. Trustees can make use of the tax deferred allowance to avoid triggering chargeable gains within the trust or can assign segments to beneficiaries prior to encashment. The Budget hasn’t impacted these tax planning strategies, but the taxation of bonds will change.

From 6th April 2027, changes to how savings income is taxed will affect the way investment bonds held within discretionary trusts are taxed.

Where a chargeable gain is taxed on the settlor or a beneficiary, any part of the gain that exceeds their savings allowances will be taxed at the new, higher savings rates.

  • Offshore bonds will continue to grow without tax being deducted internally. When a gain arises, it will simply be taxed at the new savings tax rates.

  • Onshore bonds will be affected by an increase in the tax paid within UK life funds. The internal tax rate on non-dividend income will rise to 22%, while dividends will remain tax-free.

  • When a gain arises on an onshore bond, the individual will receive a 22% tax credit to reflect tax already paid within the fund.
    • Basic rate taxpayers will have no further tax to pay.
    • Higher rate taxpayers will pay an additional 20%.
    • Additional rate taxpayers will pay an additional 25%.

  • Top slicing relief will continue to be available for both onshore and offshore bonds. The rules have been updated so that, when calculating this relief, the tax treated as already paid will reflect the new tax rates.

What This Means for Trustees

These changes could impact trust distributions and investment strategies. Trustees should review their current arrangements and consider planning ahead to manage future tax liabilities.

If you would like to discuss anything raised in this article with one of the team, please do reach out.

Read More
  • 1
  • 2
  • 3
  • …
  • 5
Contact Us

Eldon Financial Planning Limited

1 Parsons Court

Welbury Way

Newton Aycliffe

County Durham

DL5 6ZE


Telephone: (01325) 318000

Office Hours

Monday to Thursday:

9:00am – 4:30pm

Friday:

9:00am – 12:30pm

Important

The guidance and/or advice contained in this website is subject to the UK regulatory regime and is therefore restricted to consumers based in the UK.

The Financial Ombudsman Service is available to sort out individual complaints that clients and financial services businesses aren’t able to resolve themselves.

To contact the Financial Ombudsman Service please visit:

www.financial-ombudsman.org.uk

Useful Links
Important Information
Privacy Information
Recruitment

Eldon Financial Planning Limited is authorised and regulated by the Financial Conduct Authority No. 221354

Registered in England & Wales No. 4561871